Deductible
The portion of a covered loss allocated to the policyholder under the policy terms.
Free roof inspections. Clear repair and replacement options.
Roof insurance depends on the cause of damage and the actual policy. Wear, age and storm damage are different issues, and an inspection does not make the insurer’s coverage decision.
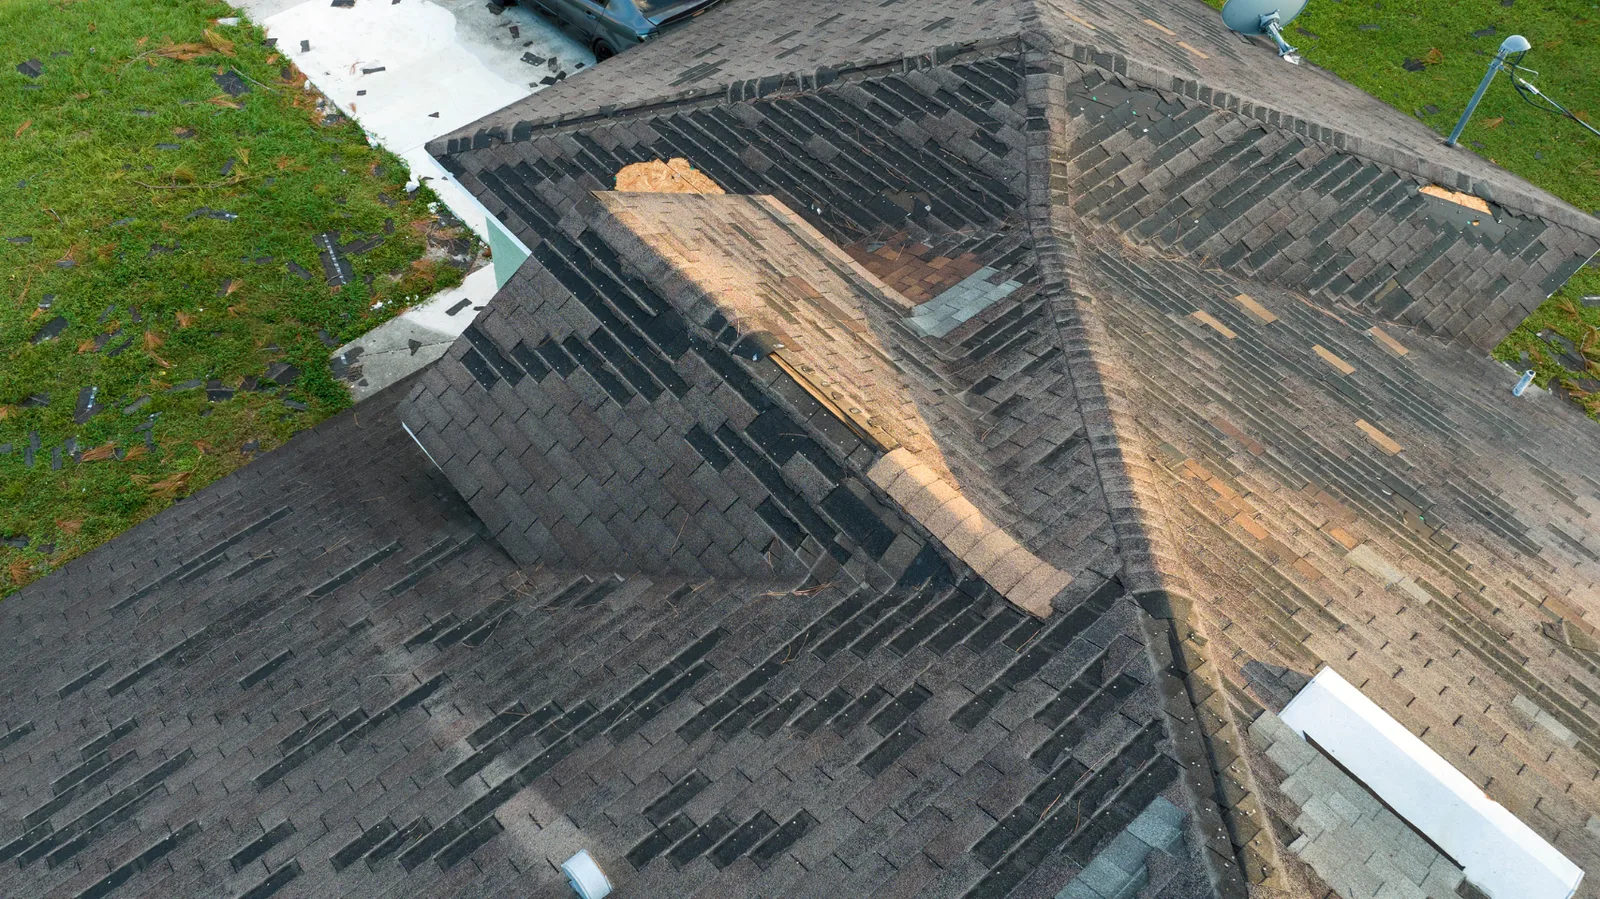
A storm-related roof assessment describes the damaged materials and the work involved. The insurer evaluates coverage under the policy, including exclusions, deductible and loss-settlement terms. A nearby hail report is context rather than proof of damage at the property.
Replacement-cost and actual-cash-value terms can change the payment sequence and owner’s share. Depreciation and the deductible should be understood with the insurer’s explanation. Report a loss promptly and follow the policy’s requirements.
The portion of a covered loss allocated to the policyholder under the policy terms.
A reduction associated with age or condition that affects an actual-cash-value calculation; any recovery depends on the policy.
The insurer’s coverage decision and the roof work needed must be understood together, without treating a contractor estimate as approval.
The useful next step connects this information to the actual roof. Tell us the property address and the concern, whether it is an active leak, material choice or a roof that keeps needing work.
A free roof inspection gives the service a chance to examine the covering and details and explain which scope fits the findings.
Tell us where the property is and what you noticed. We can start with the roof and explain the work it needs.